TL;DR

Prime made for students and young adults
- Fast, free delivery for dorm and study essentials
- Prime Video and Amazon Music included
- Member-only deals
Wood Mackenzie estimates leading sodium-ion battery manufacturers could reach cell-level cost parity with lithium iron phosphate (LFP) by late 2026. Supply agreements already exceed 70 GWh, but sodium-ion cells still cost more on average, and parity at module and system levels is not expected before after 2030. The report projects lower 20-year ownership costs for some sodium-ion storage systems, while LFP remains the more commercially mature choice for current two-to-four-hour projects.
Sodium-ion battery cells could reach cost parity with lithium iron phosphate (LFP) by late 2026, according to a Wood Mackenzie analysis reported by pv magazine Global on November 6. The report says supply agreements already exceed 70 GWh worldwide, but emphasizes that cell-cost parity would not mean sodium-ion systems are as inexpensive as LFP at the module or project level.
Wood Mackenzie’s analysis covers markets in China, the United States, Germany and India and identifies sodium-ion as a leading emerging alternative for stationary energy storage. It estimates the current global average sodium-ion battery cost at $229 per kilowatt-hour, compared with about $200/kWh for LFP. Those figures describe upfront costs; the report’s parity forecast concerns cell-level costs and applies to leading manufacturers, not necessarily every supplier or project.
The report estimates that sodium-ion systems could have 21% lower total cost of ownership over a 20-year project life, despite higher initial costs. Wood Mackenzie attributes the projected difference mainly to avoiding capacity-expansion cycles and to lower operating costs. It also says sodium-ion economics remain relatively stable across storage durations of two to four hours. These are estimates, not a guarantee of savings for every installation; project economics will depend on local costs and operating conditions.
Supply agreements totaling more than 70 GWh are in place across markets, while manufacturing plans are growing. China leads current commercialization: BYD plans to reach 30 GWh of manufacturing capacity, and CATL aims to exceed 1 GWh in sodium-ion shipments by the end of 2026. The report says agreements have been made in China, the United States and Europe, while India is still at an early commercial-validation stage. Planned production capacity currently exceeds demand, according to the analysis.
Where Sodium-Ion Could Cut Storage Costs
The potential cost advantage matters to developers planning stationary storage projects, particularly where long operating lives and future replacement or expansion costs weigh heavily in project budgets. A lower lifetime cost, if achieved, could make sodium-ion a stronger competitor even if its purchase price remains higher. Its reported ability to operate across a wider temperature range could also be useful in cold climates, where some lithium-ion installations need additional thermal management.
However, cell costs are only one part of a battery system’s price. Wood Mackenzie does not expect parity at the module and system levels until after 2030. That longer timeline is relevant for buyers comparing projects now: LFP remains the more established option for two-to-four-hour storage, while sodium-ion’s projected advantage depends on manufacturing scale, operating performance and the assumptions behind lifetime-cost estimates. Supply agreements indicate commercial interest, but do not by themselves establish that all announced volumes will be produced or purchased.
Policy may also affect the economics. The analysis points to different incentives and trade measures in China, the United States, Europe and India, which could alter the relative costs of chemistries and where manufacturers build capacity. As a result, projected parity is not a single global price point that will necessarily apply in every market.
Popular right now
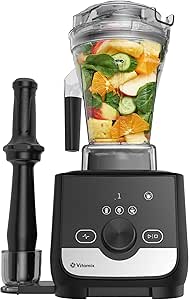
Vitamix Ascent X3 Professional-Grade Blender, 48 oz, Shadow Black

iRobot Roomba Plus 678 Robot Vacuum and Mop with AutoWash Dock

KitchenAid Artisan 5-Quart Tilt-Head Stand Mixer, Almond Cream
As an affiliate, we earn on qualifying purchases.
Commercial Scale and Policy Signals
Sodium-ion batteries use sodium rather than lithium as the charge-carrying material. The Wood Mackenzie analysis highlights supply-chain diversification, raw-material supply security, service life and temperature tolerance among the technology’s potential advantages. Its assessment focuses on stationary energy storage rather than claiming sodium-ion will replace lithium-based batteries across all uses.
China’s industrial supply chain is further along, and Wood Mackenzie estimates an 18% to 20% learning rate in China for 2026–2035. The report also describes policy measures that may influence competitiveness: China reintroduced a consumption tax on lithium-ion batteries in July 2026 while exempting sodium-ion batteries through the end of 2028; LFP batteries became subject to a 2% levy in September 2026, scheduled to rise to 4% in September 2027. In the United States, tariffs of about 58% on energy-storage cells imported from China and Section 45X production tax credits are cited as incentives for domestic manufacturing.
In Europe, carbon-footprint declarations under the EU Battery Regulation could affect technologies with different supply-chain footprints. India is backing domestic production through a $1.25 billion incentive program and tariff exemptions for some manufacturing equipment, though commercial validation remains at an early stage. The report expects 2030–2035 to be a decisive period for sodium-ion’s economic competitiveness.
“Leading manufacturers are expected to achieve cell-level cost parity with LFP batteries by late 2026.”
— Wood Mackenzie, as summarized by pv magazine Global
Costs Beyond the Cell Forecast
The report’s forecast does not establish that sodium-ion will be cheaper for all buyers by late 2026. Cell-level parity is a projection, and the source summary does not provide the underlying price assumptions, named project-level comparisons or a breakdown by manufacturer. It also does not specify how many of the more than 70 GWh in supply agreements are binding, scheduled for delivery, or likely to proceed.
The claimed 21% lifetime-cost advantage depends on assumptions about a 20-year operating period, system performance, capacity expansion and operating expenses. The source does not provide enough detail to independently assess those assumptions or determine how they vary by climate, storage duration, financing or market. Module- and system-level parity is not expected until after 2030, and LFP remains the established commercial option for projects now under development. The scale and timing of sodium-ion adoption, as well as the effect of changing policy and tariffs, remain uncertain.
Milestones Through 2035
The near-term test is whether leading manufacturers meet the late-2026 cell-cost forecast and whether planned shipments and factory capacity translate into delivered batteries. CATL’s stated goal of more than 1 GWh in shipments by the end of 2026 is one company milestone cited in the report; it is a target, not a confirmed delivery total.
Over the following years, buyers and analysts will be watching supply-agreement fulfillment, demand growth, manufacturing costs and evidence from operating projects. Wood Mackenzie identifies 2030–2035 as a decisive period for economic competitiveness, with module- and system-level parity forecast only after 2030. The report does not specify a single next review date or an updated forecast schedule.
Key Questions
What does cost parity mean in this report?
It refers to a forecast that leading sodium-ion manufacturers could match LFP battery cell costs by late 2026. It does not mean complete battery systems or installed projects will cost the same at that point.
Are sodium-ion batteries already cheaper than LFP?
No. The report gives a global average upfront cost of $229/kWh for sodium-ion, compared with about $200/kWh for LFP. It separately estimates a possible 21% lower total cost of ownership over 20 years for sodium-ion systems.
How much sodium-ion capacity is covered by supply agreements?
Wood Mackenzie’s analysis, as reported by pv magazine Global, says agreements total more than 70 GWh worldwide. The source summary does not state how much of that volume is binding or scheduled for delivery.
When could sodium-ion match LFP at the system level?
The report does not expect parity at the module and system levels until after 2030. It forecasts cell-level parity earlier, by late 2026 for leading manufacturers.
Which battery type is more established for projects being planned now?
The report says LFP remains the most commercially mature option for energy-storage projects under development with durations of two to four hours. Sodium-ion is moving toward commercial production, but adoption and project economics are still developing.
Source: pv-magazine.com